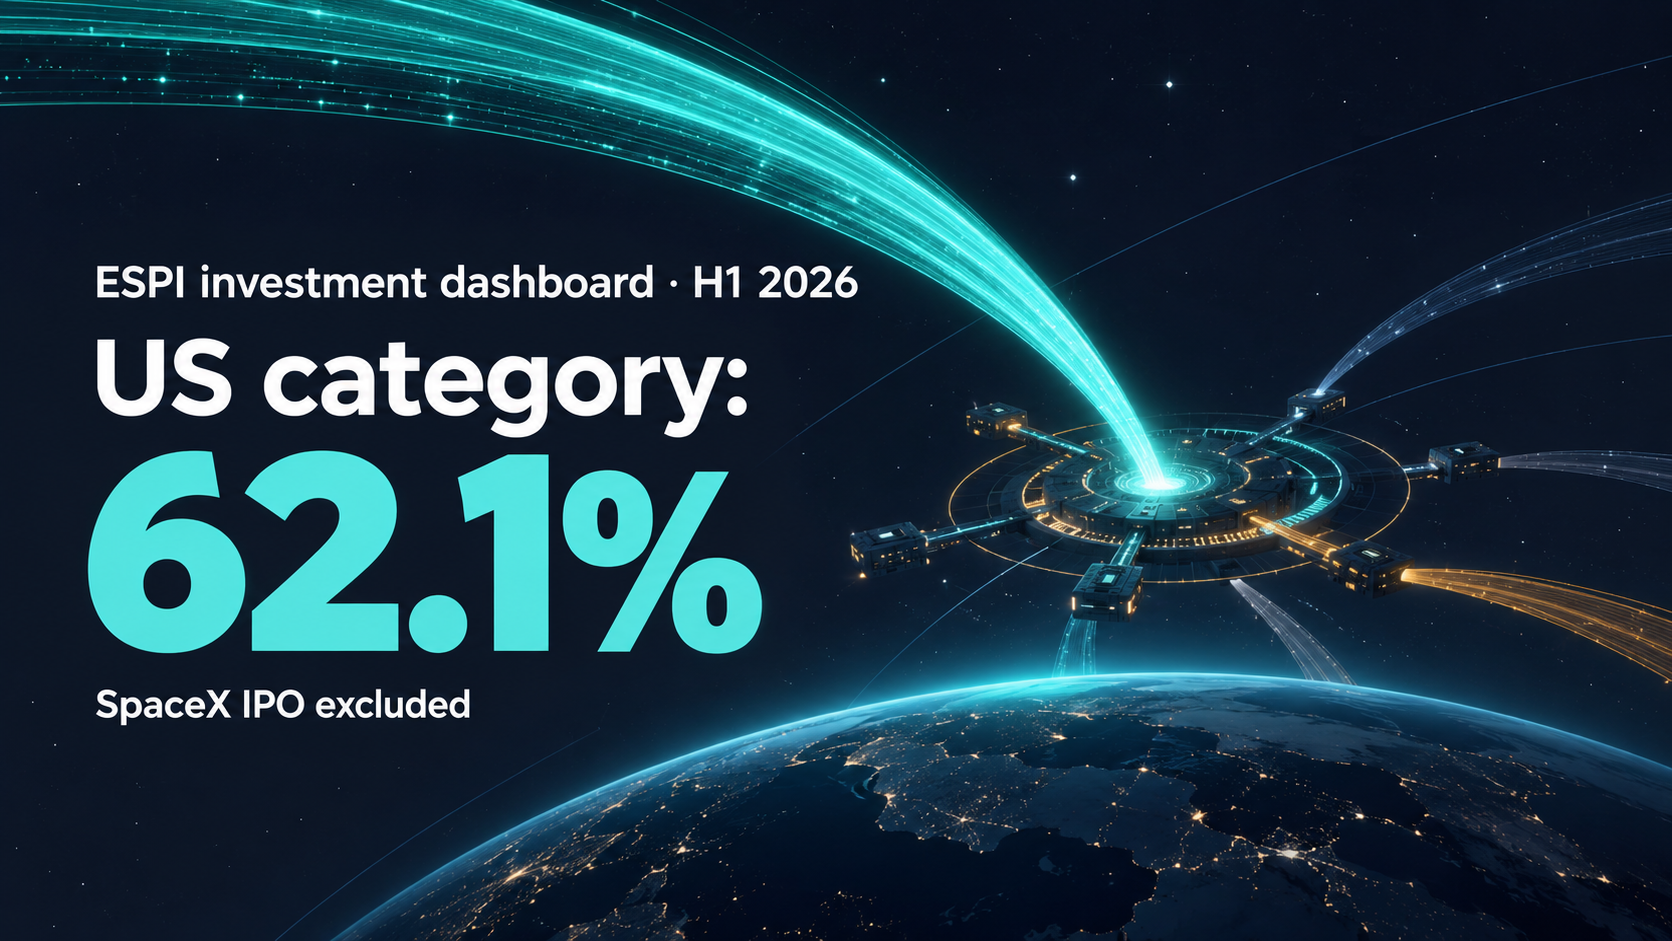
62.1 per cent is the US category's share of the investment ESPI records for the first half of 2026, EUR 6.662 billion of EUR 10.736 billion. ESPI excludes the SpaceX IPO from this visualisation. The percentage is a Space Insights calculation from the dashboard's chart values, retrieved on 12 September 2026. Space Insights.
The European Space Policy Institute's Space Venture dashboard records €10.7 billion for the first half of 2026. Beneath that total, its US category accounts for 62.1 per cent of recorded investment and Europe for 14.6 per cent. A separate view assigns 54.4 per cent to upstream activities and 30.1 per cent to the in-space economy. These distributions show why a large sector-wide funding figure carries different information for different businesses.
The figures come from the public dashboard as retrieved on 12 September, with both year controls set to 2026 and the other slicers unchanged. ESPI identifies that period as the first half and explicitly excludes the SpaceX IPO from its visualisation. The percentages here are Space Insights calculations from the chart values; they describe this recorded dataset.
The geography beneath the aggregate
| Dashboard region | Recorded investment | Share of total, calculated |
|---|---|---|
| US | €6.662bn | 62.1% |
| China | €1.981bn | 18.5% |
| Europe | €1.567bn | 14.6% |
| Rest of world | €0.526bn | 4.9% |
The unrounded regional figures reconcile exactly to €10,736,978,904. Europe's grouping includes the United Kingdom and Switzerland. It therefore describes a wider geography than the European Union. The dashboard also displays 207 deals for the selected period.
For a European supplier evaluating commercial expansion, the US share identifies a substantial concentration of recorded financing to investigate. The next useful question concerns the companies receiving that capital, their purchasing plans and the conditions for supplying them. Investment geography can help direct that investigation; procurement records and customer commitments determine which opportunities a supplier can pursue.
The European figure supports a different investigation: which financed businesses have requirements close enough to an existing product or service to become customers or partners. A regional aggregate gives a starting point for that search. The useful commercial unit remains the individual organisation and the work it needs to deliver.
A second distribution changes the planning question
The activity view allocates €5.838 billion to upstream, €3.231 billion to the in-space economy and €1.668 billion to downstream. The unrounded activity values also reconcile exactly to the same total. In-space economy represents 30.1 per cent and downstream 15.5 per cent, alongside upstream's 54.4 per cent.
ESPI's published classification places manufacturing, launch systems and satellite-capacity operations within upstream. Downstream covers businesses using space capabilities and data to deliver products and services. In-space economy covers activities beyond Earth, including services, infrastructure, research, manufacturing and exploration.
That distinction matters when translating funding news into a sales or partnership plan. Capital associated with a spacecraft manufacturer, a data-service business and an in-space infrastructure developer can imply different purchasing requirements, delivery milestones and timescales. The activity category supplies a way to organise those questions before examining individual recipients.
Connecting the views to individual decisions
Read together, the two distributions suggest a practical research sequence: identify the relevant geography, identify the activity that matches the firm's capabilities, then examine the funded businesses and their delivery commitments. This is our planning interpretation of the data. The two charts are separate distributions, so a company-level cross-tabulation would be needed to establish which regions account for which activities.
A few large transactions could shape either distribution. The next evidence to seek is therefore the disclosed deal list, followed by company plans and procurement milestones. That would reveal how much of the observed concentration corresponds to repeat demand across several customers.
The contribution of the €10.7 billion figure is clearer once those questions are attached to it. It provides a measure of recorded financing; the distributions help target the investigation that can turn that measure into a useful view of prospective customers, partners and competitors.
Sources
- 1.Space Venture half-year update: global space ventures drew 10.7 billion euro in investment — ESPI
- 2.Space Venture — dashboard and report landing page — ESPI
- 3.Space Venture public investment dashboard, year range 2026 to 2026 — ESPI
- 4.Space Venture 2025, April 2026 — Annex A, sections 7.5 and 7.9, for classification context — ESPI
Get briefings like this every Friday.
Subscribe